Masayoshi Son: The Conviction, Chaos, and Reinvention Behind SoftBank
Masayoshi Son repeatedly transformed SoftBank through concentrated technology bets, producing landmark wins, spectacular losses, and another reinvention.
View all stories about this mogul
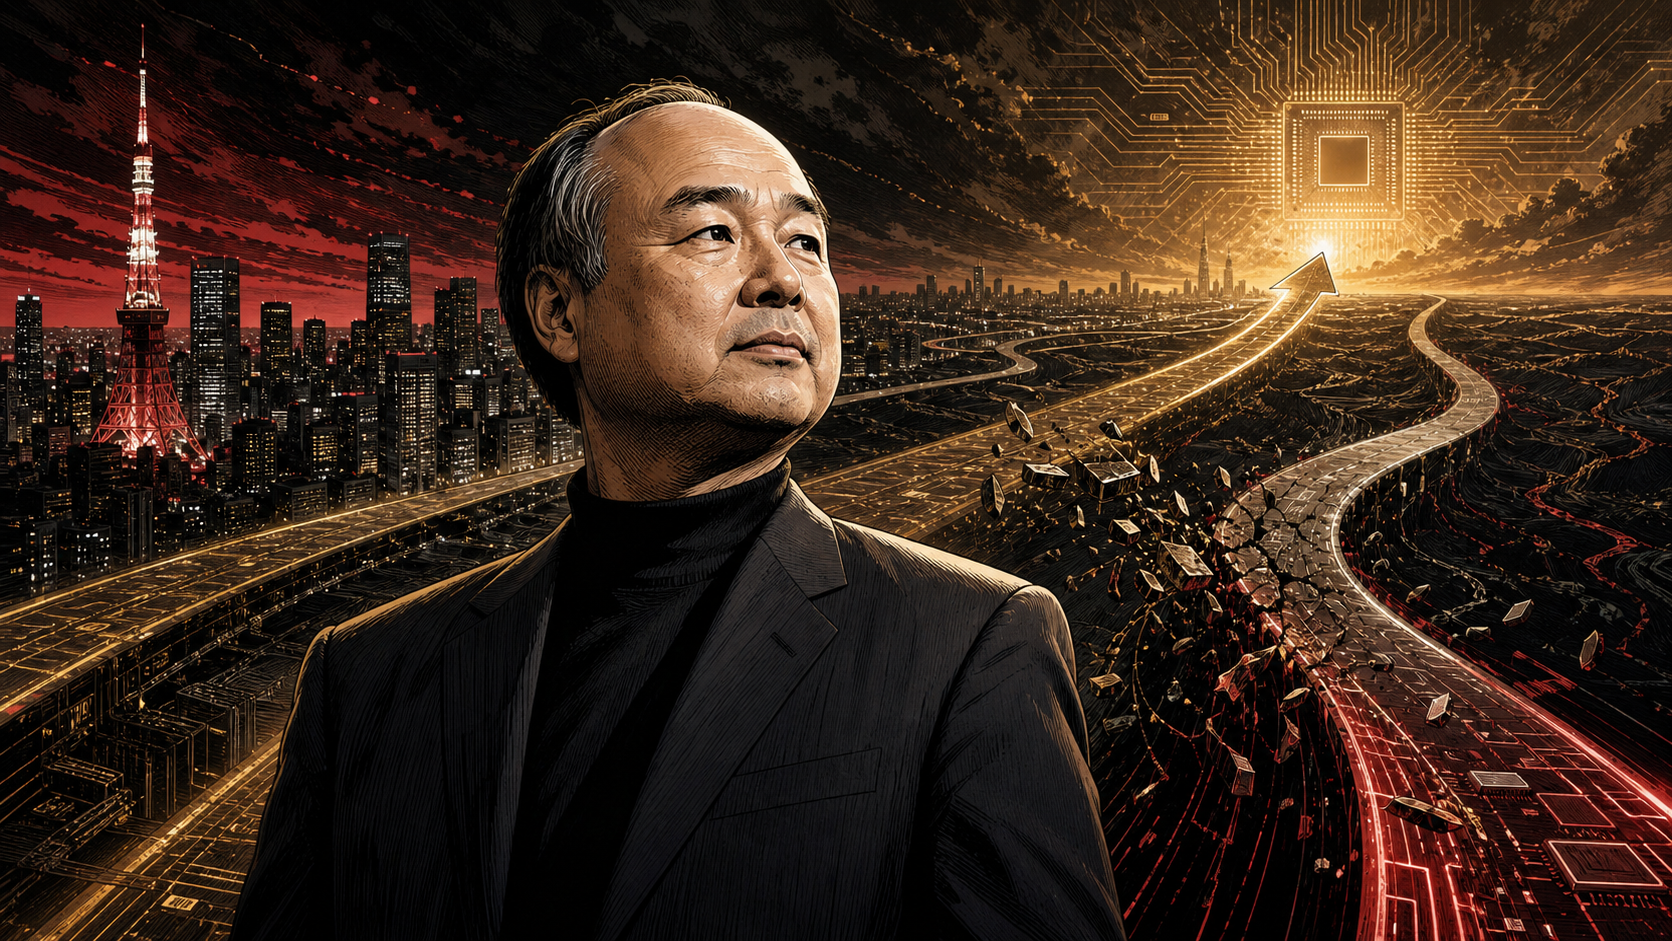
Masayoshi Son built SoftBank by behaving as if the next technological era had already arrived—and paying to meet it early.
The method produced one of the great venture investments in Alibaba, a Japanese mobile empire, and a portfolio spanning chips, telecom, internet services, and artificial intelligence. It also produced enormous drawdowns and the Vision Fund’s most controversial bets.
Son’s career is not a clean celebration of foresight or a simple warning about excess. It is a study in concentrated conviction: how it creates speed, how capital amplifies judgment, and why reinvention must eventually answer to discipline.
How Did Son Turn Software Distribution Into a Technology Group?
Born in Japan and educated in the United States, Son founded SoftBank in 1981 as a software distributor. The name signaled an ambition larger than moving boxes: he wanted the company to become a bank of software and information.
SoftBank expanded through computer trade shows, publishing, and internet investments. Son’s willingness to buy strategic positions before markets matured became the operating pattern. During the dot-com boom, his wealth and SoftBank’s value surged, then collapsed dramatically when the bubble broke.
The crash did not end the company. Son rebuilt around broadband and mobile telecommunications, eventually acquiring Vodafone’s Japanese operation. SoftBank became a major carrier, giving it cash flow, customers, and distribution rather than only minority stakes.
The Alibaba investment became the defining proof of Son’s instinct. A relatively early commitment to Jack Ma’s company grew into extraordinary value as Chinese e-commerce expanded. That win strengthened both SoftBank’s balance sheet and Son’s belief that a few massive outcomes could justify many failures.
Why Did the Vision Fund Change Venture Capital?
Announced in 2016 and launched with major external backing, the Vision Fund brought an unprecedented scale to technology investing. It could write checks large enough to reshape a startup’s strategy and competitive market in one transaction.
The thesis was that artificial intelligence and connected data would transform industries. Backing category leaders with abundant capital could let them invest faster, enter more markets, and outrun rivals. For founders, SoftBank offered resources that traditional venture rounds could not match.
Scale changed incentives. Companies could subsidize growth, acquire customers aggressively, and postpone hard questions about unit economics. Large private valuations created headline gains before exits proved them. Governance became harder when a powerful investor wanted speed and founders retained substantial control.
The Vision Fund did not invent venture excess, but it industrialized it. Competitors raised larger funds. Startups designed plans around capital availability. The boundary between financing advantage and operational distortion became difficult to see during rising markets.
What Did the Losses Reveal About Son’s Method?
WeWork became the emblem of the problem. Its failed 2019 public offering exposed governance concerns, heavy losses, and a gap between private narrative and public-market scrutiny. SoftBank committed additional resources and absorbed painful consequences.
Other portfolio companies faced their own downturns as interest rates rose and investors demanded profitability. Valuation losses demonstrated that diversification by company count does not eliminate exposure when many businesses depend on the same cheap-capital environment.
Son responded by shifting between offense and defense: selling assets, repurchasing shares, reducing new investment, and emphasizing liquidity. SoftBank’s public reporting made the volatility visible from quarter to quarter.
Arm offered a different center of gravity. SoftBank acquired the chip designer in 2016. After a proposed sale to Nvidia failed under regulatory pressure, Arm returned to public markets in 2023. Its architecture’s importance across mobile and emerging AI workloads gave Son another strategic platform around which to frame SoftBank’s future.
Is SoftBank Now an AI Company—or Still Son’s Portfolio?
Son now presents artificial superintelligence as the next organizing idea. SoftBank’s assets, especially its Arm position, provide exposure to the computing layer beneath that ambition. Yet the central governance question remains: can visionary concentration coexist with capital discipline?
SoftBank’s history shows that Son can rebuild after severe losses. It also shows that a celebrated recovery can reinforce the habits that caused the previous crisis. The institution must distinguish long-duration conviction from refusal to update.
Key facts and timeline
| Milestone | Why it mattered |
|---|---|
| 1981 founding | Began SoftBank as a software distribution business |
| Dot-com expansion and crash | Established both Son’s reach and appetite for risk |
| Alibaba investment | Produced a landmark gain and funded later ambition |
| Japanese mobile expansion | Added operating scale and recurring cash flow |
| 2016 Arm acquisition | Secured a strategic position in chip architecture |
| Vision Fund era | Applied unprecedented capital to private technology companies |
FAQ
Who founded SoftBank? Masayoshi Son founded SoftBank in Japan in 1981.
What was Son’s most famous investment? His early investment in Alibaba became the best-known financial success associated with SoftBank.
Why was the Vision Fund controversial? Its scale accelerated companies but also raised concerns about valuation, governance, subsidies, and pressure to pursue growth before durable economics.
Why is Arm important to SoftBank? Arm designs processor architecture used widely across computing, giving SoftBank strategic exposure to the semiconductor layer of AI and connected devices.
Son’s advantage has always been his willingness to act before consensus. The durable lesson is that vision and governance are not alternatives. The larger the bet, the more an institution needs both.
💡 Key Insights
- ▸ Concentrated conviction can transform a company and magnify its errors.
- ▸ Access to capital is not a substitute for operating discipline.
- ▸ A landmark investment can reshape the investor as much as the portfolio.
- ▸ Reinvention is a capability, but it does not erase governance risk.