Alfred Nobel Made an Explosives Fortune and Left It to Fund Prizes
Alfred Nobel’s 1895 will redirected his industrial wealth into five annual prizes, but relatives, tax disputes and an unfinished legal structure stood in the way.
View all stories about this mogul
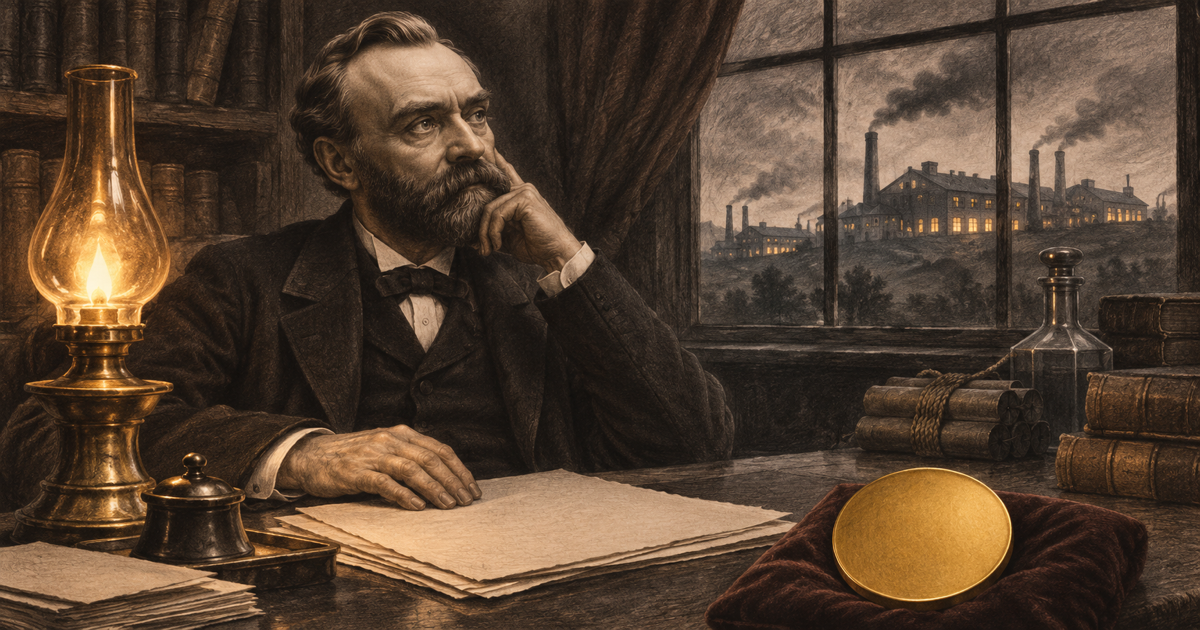
On 27 November 1895, Alfred Nobel signed a will in Paris directing that his remaining estate finance five annual prizes. The document listed securities held in banks across Europe, property in France and Italy, patents, royalties and money owed to him. An international industrial fortune was to become an investment fund whose income rewarded scientific discoveries, literature and work for peace. Nobel named the institutions that would select the recipients. The foundation needed to administer the money did not yet exist. His will survives in full.
Nobel died in Sanremo on 10 December 1896. His instructions then became a practical problem for two executors: establish control over assets scattered across jurisdictions, address family objections and create an organization capable of carrying out an indefinite obligation. The first prizes would not be awarded until 1901. The familiar medals and ceremonies followed years of negotiation over property, taxation and authority.
The business history behind that settlement matters. Nobel had accumulated wealth through inventions that made powerful explosives more useful, an international network of industrial interests and investments beyond his laboratories. His final decision changed who would benefit from that wealth. It also required his successors to exchange much of the commercial structure that had produced the fortune for a different financial arrangement.
A dangerous product needed more than a patent
Nobel came from an engineering family. Born in Stockholm in 1833, he moved with his family to St. Petersburg in 1842. His father, Immanuel, operated an engineering business there. Alfred’s later career combined scientific experimentation with the commercial demands of manufacturing: raising money, protecting inventions and finding ways to produce them repeatedly.
Nitroglycerine presented an unusually severe version of that manufacturing problem. Its explosive force promised industrial applications, but handling it exposed workers and customers to considerable danger. An invention that worked under controlled conditions still needed a dependable means of initiation and a form that could be handled more safely. Those were separate technical obstacles, and overcoming them was central to Nobel’s business.
The Royal Swedish Academy of Sciences records that Nobel worked with his father and younger brother Emil on explosive technology patented in 1863. Industrial production of the product known as blasting oil began with foreign loans. In 1864, a laboratory explosion killed several people, including Emil. Nobel continued his work, and the family established Nitroglycerin AB. Production subsequently extended to Germany, Norway and the United States. The academy’s account documents both the financing and the fatal accident.
Dynamite addressed part of the handling problem by combining nitroglycerine with kieselguhr, an absorbent material. Nobel patented dynamite in 1867. The mixture made the explosive easier and safer to handle, although it remained a hazardous industrial product. Its commercial significance lay in making explosive power more usable for work such as mining and construction. The invention connected a laboratory result to customers who needed to break rock on a large scale.
The distinction between explosive power and a marketable product helps explain Nobel’s position. He did not invent nitroglycerine. His contribution included ways to initiate it and incorporate it into a more manageable explosive. Customers needed a workable system, rather than an isolated chemical discovery. Nobel’s industrial opportunity depended on solving enough of those practical problems to support production and use.
An inventor became an international industrialist
Nobel’s work continued after dynamite. In the 1870s he developed blasting gelatine, also known as gelignite; ballistite, a smokeless propellant for firearms, followed. These products served different requirements, extending his commercial interests beyond the original dynamite formulation. They also placed his work in both civilian industry and military supply. A history that treats all his explosives as interchangeable misses that distinction.
By the end of his life, Nobel held 355 patents. The Nobel organization describes an industrial network of more than 90 factories in 20 countries. Those figures describe the reach of his career, rather than 355 wholly separate products or a single uniform corporation. Patents, manufacturing companies and financial holdings formed overlapping parts of his business. The Nobel organization’s biographical record provides the chronology and scale.
His development as an industrialist therefore involved more than accumulating inventions. A patent could establish a legal claim, but manufacturing required capital and organization. An overseas factory added production capacity while placing the business under another country’s commercial and legal arrangements. By distributing his interests internationally, Nobel gained a broader industrial presence and left his estate a more complicated collection of assets to administer.
The surviving will gives a particularly useful view of that complexity. Nobel identified deposits with the Union Bank of Scotland in Glasgow and London, several institutions in Paris, bankers in Berlin, the Russian Central Bank and Skandinaviska Kredit Aktiebolaget in Gothenburg and Stockholm. He also mentioned securities held with his nephew Emanuel in Petersburg and assets in his strongbox on Avenue Malakoff in Paris.
This was a financial inventory written by an owner who expected others to reconstruct his affairs. It included accounts receivable and patent income alongside securities and real estate. The executors would need his books and papers to establish the details. Even before any dispute arose, carrying out the will required understanding different kinds of property: a bank deposit could be collected, a security transferred or sold, and a royalty claim might continue to produce income.
The estate also reached beyond explosives. The Norwegian Nobel Institute’s history identifies holdings in Russian oil and mining companies among Nobel’s assets. His wealth consequently cannot be understood simply as the accumulated proceeds from selling dynamite. Industrial invention supplied the best-known foundation of his fortune; investments and corporate interests broadened it. The institute describes the asset mix and its eventual liquidation.
The will prescribed a new use for capital
Nobel’s testament began with individual bequests. His nephews Hjalmar and Ludvig were each to receive 200,000 crowns, Emanuel 300,000, and his niece Mina 100,000. Other relatives and acquaintances received specified amounts. The document also provided annuities for people who had worked for him and distinguished money he owned from money he merely held for others.
That distinction is easy to overlook in a story about a large charitable gift. Nobel instructed that funds belonging to his brother’s children be repaid and separately identified money belonging to Elise Antun. These were obligations to settle before determining what remained available for his central project. The prize fund was to receive the residual estate after the specified arrangements had been addressed.
The principal instruction established a financial sequence. His executors were to realize the remaining estate, invest the capital in safe securities and use the interest for annual prizes. Nobel was prescribing both a purpose and a source of recurring income. The capital would support awards over time, rather than be distributed immediately among a first group of beneficiaries.
The instruction also changed the relationship between the money and the businesses that had generated it. Nobel did not require the prize administrators to continue operating his industrial interests as a permanent family concern. They needed an investable fund. Commercial holdings were therefore assets to be converted into support for the awards, with the executors responsible for accomplishing that conversion.
The interest was to be divided into five equal parts, covering physics, chemistry, physiology or medicine, literature and peace. Each category had its own criteria. Physics included discoveries or inventions; chemistry included discoveries or improvements. The peace provision referred to fraternity between nations, reducing standing armies and promoting peace congresses. These were distinct judgments that could not be reduced to a single financial measure.
Nobel then assigned those judgments to existing institutions. The Swedish Academy of Sciences would handle physics and chemistry, the Karolinska institution medicine, and the Swedish Academy literature. A committee of five people elected by the Norwegian parliament would select the peace recipient. He explicitly instructed the selectors to disregard nationality. The structure gave an international purpose to a fortune whose assets were already international.
The result separated two kinds of responsibility. Someone had to safeguard and administer the capital; other bodies had to evaluate achievements. Nobel named the selectors but left substantial organizational work unfinished. The testament established the destination of the money more clearly than the administrative machinery needed to deliver it. These provisions appear together in the original testament.
The executors inherited an institution that did not exist
Nobel appointed Ragnar Sohlman and Rudolf Lilljequist as executors. His will anticipated that Sohlman would bear the greater workload and provided him with compensation of 100,000 crowns, compared with 50,000 for Lilljequist. That provision acknowledged the burden of settling the affairs. It did not supply a ready-made organization to receive and manage the principal bequest.
The Library of Congress’s legal history identifies the absence of such an institution as a fundamental weakness. The executors had to establish it while resolving the estate. They were carrying out two connected projects: settling a deceased businessman’s property and constructing the legal framework for a permanent prize system. Success in one would be insufficient without success in the other.
Nobel’s international life complicated the first project. He died in Italy, had a home in Paris and owned property in Sweden. Determining his legal domicile mattered because it affected where the estate would be administered and objections considered. Residence, asset location and governing law were practical questions with consequences for the amount and control of the eventual fund.
Taxation added another layer. The Library of Congress records a Swedish Supreme Court decision in 1899 allowing Nobel’s French property to be taxed in France and included in the Swedish taxable estate. The court permitted the French tax payment to be deducted as a debt of the estate. That was a specific adjustment to a cross-border problem, rather than a blanket exemption for money intended for prizes.
Relatives also contested the arrangements. A settlement was needed to resolve family claims, while the institutions expected to award the prizes had to operate within an agreed framework. The eventual foundation thus emerged from negotiations as well as from Nobel’s instructions. A signature on the will had expressed his intention; the executors still needed to make that intention legally and financially workable.
This part of the history places Sohlman and Lilljequist inside the business story. Their task concerned title to assets, competing claims, administrative powers and the conversion of property into usable capital. Nobel had delegated the work without specifying every mechanism. The executors’ decisions helped determine whether the promised awards would become a functioning institution. The Library of Congress traces the domicile, tax and organizational disputes.
Factories and securities became a prize fund
Liquidation connected the commercial fortune to the new institution. Nobel’s executors had to gather and sell assets before the resulting capital could support awards. The Norwegian Nobel Institute records that securities were sold in London and Stockholm and that the fund acquired approximately 31.5 million Swedish kronor. Responsibility for the assets passed to the newly established Nobel Foundation in 1900.
This conversion changed the risks attached to the wealth. Interests in industrial enterprises carried exposure to their products, operating conditions and markets. A securities fund carried investment risks and the continuing obligation to finance prizes and administration. Nobel’s instructions sought safe investments, but even that principle required implementation: the fund needed assets that generated income and an organization authorized to manage them.
For an endowed prize, the distinction between capital and annual income is consequential. Spending the whole fund could finance a large immediate distribution but end the recurring awards. Preserving capital while distributing income offered a route to continuity. It also made the future scale of the prizes dependent on investment results and the rules governing how those results could be used.
The foundation’s establishment supplied the missing institutional owner and administrator. King Oscar II approved its statutes on 29 June 1900. The first Nobel Prizes followed on 10 December 1901, the fifth anniversary of Nobel’s death. The delay between death and awards measures the work required to translate an individual’s instructions into a continuing organization.
It is tempting to compress those years into a simple statement that Nobel left his money to the Nobel Foundation. That formulation reverses the sequence. The foundation had to be created to carry out the bequest. Its existence was an outcome of the estate settlement, rather than a resource available to Nobel’s executors from the beginning.
The financial and administrative settlement also made the division of duties practical. A central organization could manage assets while specialist institutions selected recipients. The arrangement allowed the prize system to use expertise that Nobel did not expect his estate administrators to possess. Managing a portfolio and deciding which scientific discovery deserved recognition required different processes and different authority.
The legacy rested on a transfer of control
The categories Nobel selected reflected interests broader than explosives. Literature received a share equal to physics or chemistry. Peace stood alongside scientific work rather than being financed from whatever happened to remain. In the testament’s financial design, these fields were equal claims on the income available for prizes, even though evaluating achievement within them required very different judgments.
His instruction on nationality was equally concrete. Nobel wanted the most deserving candidate considered regardless of whether that person was Scandinavian. He was asking institutions rooted in Sweden and Norway to make awards with a wider field of consideration. The rule constrained the use of his money after death: local institutions would administer an explicitly international ambition.
There were limits to what the document could settle. Phrases about the greatest benefit or outstanding literary work required interpretation. The will could allocate capital and appoint selectors, but it could not anticipate every future discovery, political dispute or disagreement over merit. The continuing institution would have to make decisions that the founder could no longer supervise.
That is the central transfer in Nobel’s final business act. He accumulated property through inventions, companies and investments, then assigned the income from the residual fortune to purposes administered by others. Family members received specified provisions, but the principal project did not depend on descendants choosing each year to renew his commitment. The testament sought to make that commitment durable through an endowed structure.
The survival of the prizes should not obscure the work between intention and execution. Nobel supplied the wealth and instructions. Executors, courts, relatives and awarding institutions helped establish the arrangement that could carry them out. The bequest became effective through asset sales, legal decisions, negotiated terms and approved statutes. Its history is therefore a case study in organizing ownership after a founder’s death as well as in philanthropy.
Nobel’s industrial career and his prize system belong to the same financial history. The laboratories and businesses explain where the capital came from; the will explains the use he prescribed for what remained. The decisive change was that a fortune attached to an inventor’s commercial interests became capital administered for recurring awards. On 10 December 1901, recipients could finally receive the first tangible results of that change.
Frequently asked questions
How did Alfred Nobel make his fortune?
He earned wealth through explosives inventions, patents and international industrial interests, alongside investments that included Russian oil and mining companies.
What did Alfred Nobel’s will establish?
His 1895 will directed his remaining estate into a fund financing annual prizes in physics, chemistry, physiology or medicine, literature and peace.
Why did the first Nobel Prizes wait until 1901?
After Nobel died in 1896, executors had to settle legal and family issues, realize assets and establish the Nobel Foundation.
💡 Key Insights
- ▸ Nobel’s wealth combined explosives inventions with international corporate and investment holdings.
- ▸ His will assigned investment income to prizes rather than requiring continued family management of his businesses.
- ▸ The Nobel Foundation had to be created after his death to administer the bequest.
- ▸ Legal settlements and asset liquidation were essential to the first awards in 1901.
Sources
- Alfred Nobel’s will — full text, Nobel Foundation translation hosted by the University of Barcelona ↗
- Royal Swedish Academy of Sciences — Alfred Nobel ↗
- NobelPrize.org — The man behind the prize ↗
- Norwegian Nobel Institute — Alfred Nobel’s fortune ↗
- Library of Congress — Alfred Nobel’s will and its legal history ↗
- Norwegian Nobel Institute — Alfred Nobel’s will ↗